 Alliance Equity Research
GE Aerospace Raises Its Outlook as Maintenance Growth Supports Commercial Earnings
GE Aerospace’s higher annual guidance reflects stronger commercial services growth and a smaller expected GE9X earnings impact. Maintenance volume and pricing lifted commercial profit at a broadly stable margin. The remaining cash target implies faster year-over-year growth than GE delivered in the first nine months.
Higher earnings have strengthened the annual outlook
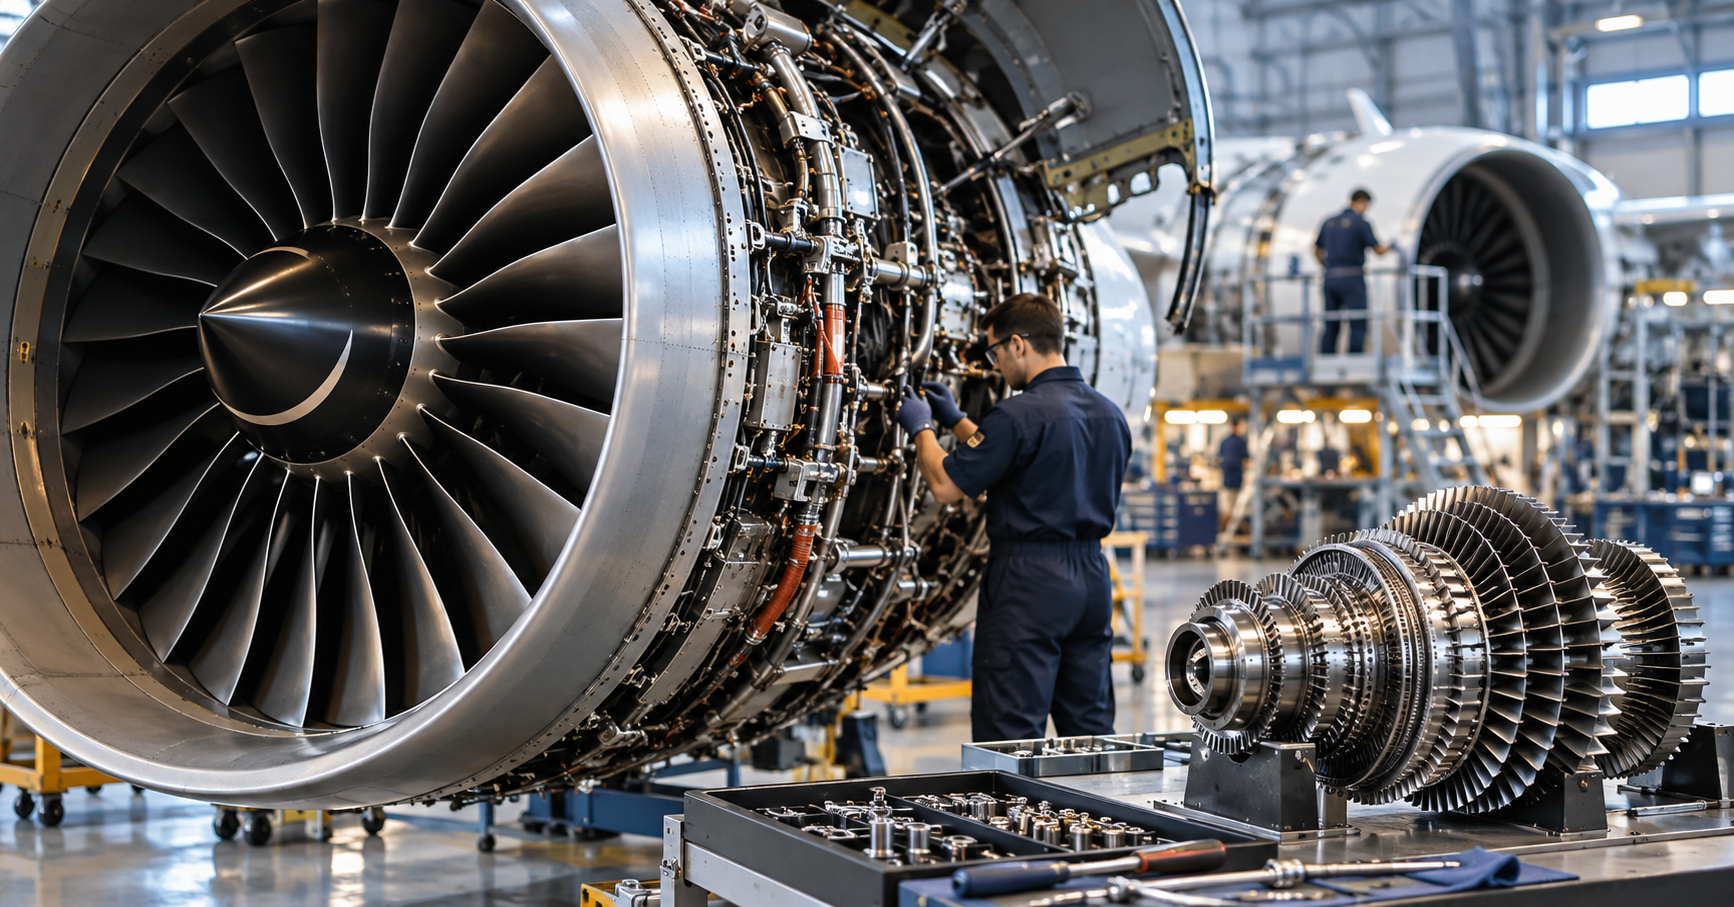
GE Aerospace raised its 2026 guidance on October 20, supported by demand for aircraft engines, maintenance and replacement parts. The business earns revenue both when engines enter service and through the work required to keep them flying. Improving maintenance capacity helps convert that installed base into current revenue.
Third-quarter adjusted operating profit rose 30% year over year to $2.988 billion, while free cash flow fell 14% to $2.042 billion. Over the first nine months, however, free cash flow increased 13% to $6.728 billion. The quarterly decline sits within a year of higher cash generation, supported by growth in the commercial engine and maintenance business. Adjusted operating profit and free cash flow are company-defined non-GAAP measures.
The revised outlook reflects stronger commercial services growth and a smaller expected earnings impact from GE9X engines, which power Boeing’s 777X aircraft. GE now expects Commercial Engines & Services operating profit of $10.5 billion–$10.6 billion for 2026, up from $10.25 billion–$10.35 billion. The central improvement is higher earnings from the commercial business; the remaining cash requirement needs to be assessed against both prior-year performance and the working capital absorbed by growth.
Maintenance demand becomes revenue when capacity is available
An aircraft engine remains an economic relationship long after delivery. Airlines and lessors require inspections, repairs, replacement components and overhaul work throughout its operating life. GE’s TrueChoice services offering addresses those needs through service and materials arrangements across the engine lifecycle. The scope and timing of work affect both customer aircraft availability and GE’s revenue.
A maintenance backlog creates an opportunity only as facilities, labor and components become available to complete the work. Spare parts also support maintenance performed outside GE’s own shops. Consequently, the operating variables extend beyond airline demand to workshop throughput, the amount of work required per visit and parts availability.
The quarterly presentation reports year-over-year growth of 12% in internal shop-visit revenue and more than 20% in spare-parts revenue. Higher shop-visit volume and heavier workscope, meaning more repair and overhaul work per visit, contributed to the increase. GE also reported an approximately two-week reduction in turnaround time for LEAP engines, a family used on narrow-body passenger aircraft. Faster shop flow helps return engines to customers and makes capacity available for further maintenance.
Commercial Engines & Services generated $10.34 billion of third-quarter revenue. Services contributed $7.74 billion, approximately three-quarters of that segment’s revenue; equipment supplied the remainder. This is a breakdown within the commercial segment, separate from GE’s Defense & Propulsion Technologies business. The mix explains why maintenance performance has such influence over the commercial earnings outlook.
Commercial segment operating profit rose 21% to $2.887 billion, according to the results release, driven by higher services volume and pricing. Its margin was 27.9%, compared with 28.0% a year earlier, as mix and inflation offset those benefits. Earnings growth therefore came primarily from greater activity at a broadly maintained margin. At group level, lower corporate costs and eliminations also contributed: their combined charge fell from $525 million to $373 million, while defense segment profit increased from $440 million to $475 million. Commercial growth explains most of the $689 million increase in group adjusted operating profit, but the full 30% increase should not be attributed to maintenance alone.
What the revised guidance requires from the fourth quarter
GE’s July outlook called for annual adjusted operating profit of $10.55 billion–$10.75 billion and free cash flow of $8.9 billion–$9.2 billion. October’s increases lift the respective midpoints by $300 million and $200 million.
| US$ billion | Previous annual guidance | Revised annual guidance | Nine-month actual | Implied fourth quarter |
|---|---|---|---|---|
| Adjusted operating profit | 10.55–10.75 | 10.90–11.00 | 8.262 | 2.638–2.738 |
| Free cash flow | 8.90–9.20 | 9.10–9.40 | 6.728 | 2.372–2.672 |
Subtracting nine-month actuals from the revised annual targets leaves fourth-quarter adjusted operating profit of $2.638 billion–$2.738 billion and free cash flow of $2.372 billion–$2.672 billion. Profit can therefore be approximately 8%–12% below Q3 while still meeting guidance; cash flow needs to be approximately 16%–31% above Q3. These are the results implied by the annual ranges, rather than separate quarterly forecasts issued by management.
The fourth-quarter 2025 results provide a more relevant seasonal reference than Q3 alone. GE generated $1.760 billion of free cash flow in that quarter, so the current implied requirement represents approximately 35%–52% year-over-year growth. That exceeds the 13% increase delivered over the first nine months of 2026. The comparison establishes the scale of the remaining increase; it does not establish that a sequential rise is unusual or that a particular receivables balance will be collected before year-end.
GE’s free-cash-flow definition starts with operating cash flow, deducts capital spending, includes proceeds from property disposals and adds back specified separation and restructuring cash expenditures. In Q3, operating cash flow was $2.203 billion; $337 million of capital spending, $122 million of disposal proceeds and $54 million of cash-expenditure add-backs reconciled it to $2.042 billion of free cash flow. The annual targets and prior-year comparison above use this disclosed measure consistently.
Working capital explains why output and cash can diverge
The September quarterly filing reports that changes in working capital consumed approximately $1.8 billion in the first nine months, about $0.9 billion more than a year earlier. Higher activity increased amounts awaiting collection, while revenue recognition on service contracts could precede billing. Payments to suppliers also absorbed cash. These effects help explain why higher earnings did not translate into an equivalent increase in cash generation.
The filing attributes the additional year-over-year working-capital cash use to approximately $1.1 billion from receivables, $0.5 billion from contract balances and deferred income, and $0.6 billion from accounts payable. Inventory movements and progress collections offset about $1.2 billion of those effects. The rounded components broadly reconcile to the additional $0.9 billion cash use. These figures describe changes versus the prior nine-month period, not the cash outflow attributable to each category in Q3.
The cash outlook consequently depends on the interaction of collections, billing, supplier payments and investment as output expands. The nine-month disclosure does not specify a Q4 collection schedule or quantify a reversal of the working-capital outflow. Stronger profit provides a larger source of cash, but the timing of those operating movements determines how much is retained by December. This limits how confidently the implied Q4 increase can be attributed to collections alone.
Capacity investment extends beyond the current outlook
GE’s proposed Consolidated Precision Products acquisition extends its effort to increase supply capacity. CPP manufactures engineered aerospace castings and subassemblies and has supplied GE for more than fifteen years. The $11.75 billion purchase is expected to use approximately $7 billion of cash and $4.75 billion of new debt, with closing expected in the second half of 2027, subject to approvals and customary conditions. Sustained cash generation would support flexibility ahead of that commitment; the acquisition is a separate use of capital from the current annual operating outlook.
Higher commercial earnings support the revised outlook
GE’s results support a stronger earnings assessment because maintenance volume, more extensive work per visit and pricing are increasing commercial profit while its margin remains broadly stable. The raised commercial segment guidance makes that contribution explicit. Continued output growth will be more valuable if GE can preserve profitability as it invests in capacity and absorbs inflation.
For year-end cash delivery, the relevant comparison is the implied $2.37 billion–$2.67 billion against $1.76 billion in Q4 2025, alongside the working capital required to sustain higher activity. Delivery within that range with stable commercial margins would support the view that earnings growth is translating into greater financial capacity. Further cash absorption by receivables or contract balances would temper that assessment, even if the annual profit target is achieved.
This material is provided for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security.
Companies Discussed
About AER Insights
Alliance Equity Research publishes timely insights on company-specific developments, industry trends, capital markets activity, and emerging investment themes across global public markets, with a particular focus on undercovered companies, sectors, and developments that often receive limited attention from mainstream financial research. Our analysis focuses on the financial, strategic, and valuation implications behind the headlines, using company disclosures, filings, market data, and sector context to help investors understand what matters, why it matters, and what to watch next.
Get AER Insights by Email
Receive new AER Insights and research updates in your inbox.
Related Insights
 Mining & Critical Minerals
Cornish Metals’ £135 Million Raise Would Unlock South Crofty Funding at a Dilutive Price
Cornish Metals has proposed the equity financing needed to advance South Crofty and release its escrowed bond funding. The package also converts shareholder loans and introduces Glencore as a buyer of future production. Existing shareholders gain a clearer construction path while sharing the eventual returns across substantially more shares.
 Capital Markets & M&A
Silgan’s Trivium Deal Pairs a Cash Release With a Demanding Synergy Plan
Silgan’s proposed Trivium combination would release $2.3 billion in cash and preserve majority ownership of an enlarged metal-packaging business. Its $225 million savings target represents approximately 24% of combined pre-synergy adjusted EBITDA, making integration central to the economics and the intended eventual separation.
 Industrials & Aerospace
Schneider’s Data-Center Growth Supports a Software Expansion With Demanding Acquisition Economics
Schneider Electric has raised its outlook again as demand for data-center power and cooling equipment strengthens. Its proposed PTC acquisition would extend the business into product engineering software, but the purchase economics depend on earnings benefits that exceed the identified cost savings.
 Industrials & Aerospace
Volution’s Acquisition Strategy Is Broadening Its Markets and Increasing Its Funding Needs
Volution’s latest results show how a ventilation manufacturer can grow through acquisitions while improving operating margins. Expansion into mining and European heat recovery adds new customers, but acquisition payments are absorbing cash and increasing the importance of returns on invested capital.
About Alliance Equity Research
Alliance Equity Research publishes independent and company-sponsored equity research on undercovered, emerging, and high-potential public companies globally. Our analyst-built, model-backed research combines fundamental business analysis, financial forecasting, and valuation.
Email: info@alliancekp.com · Website: https://allianceequityresearch.com
For detailed company research, financial models, or coverage inquiries, contact our research team.
Research commentary for informational purposes. This document does not constitute personalized investment advice or a Buy, Hold, or Sell recommendation. For important disclosures, including information about research sponsorship and potential conflicts of interest, visit allianceequityresearch.com/disclosures.