 Alliance Equity Research
Silgan’s Trivium Deal Pairs a Cash Release With a Demanding Synergy Plan
Silgan’s proposed packaging combination would deliver $2.3 billion of cash while preserving control of the enlarged metal business. The structure creates financial flexibility, but the acquisition’s lower advertised multiple depends on savings equivalent to almost half of Trivium’s recent adjusted EBITDA.
An acquisition that also releases capital
Silgan Holdings, the manufacturer behind food cans, dispensing systems and other consumer packaging, announced on October 19 a proposed combination of its metal-packaging operations with Trivium Packaging. American Industrial Partners, an industrial private-equity investor, would provide equity alongside financing raised by the combined business. Silgan would receive approximately $2.3 billion in cash and retain a 60% controlling interest.
The structure connects two objectives: expanding the metal-packaging business and releasing capital for Silgan’s remaining operations. Shareholders would retain exposure to the combined operation’s earnings, while sharing its future equity returns with AIP. Their outcome depends on both the financing terms and the operating improvements achieved after closing.
The strongest economic attraction is the opportunity to combine established manufacturing businesses and remove overlapping costs. However, the proposed savings are large relative to Trivium’s existing earnings. Investors should assess the acquisition using its current earnings base alongside the more favorable economics management expects after integration.
The businesses have a practical commercial connection
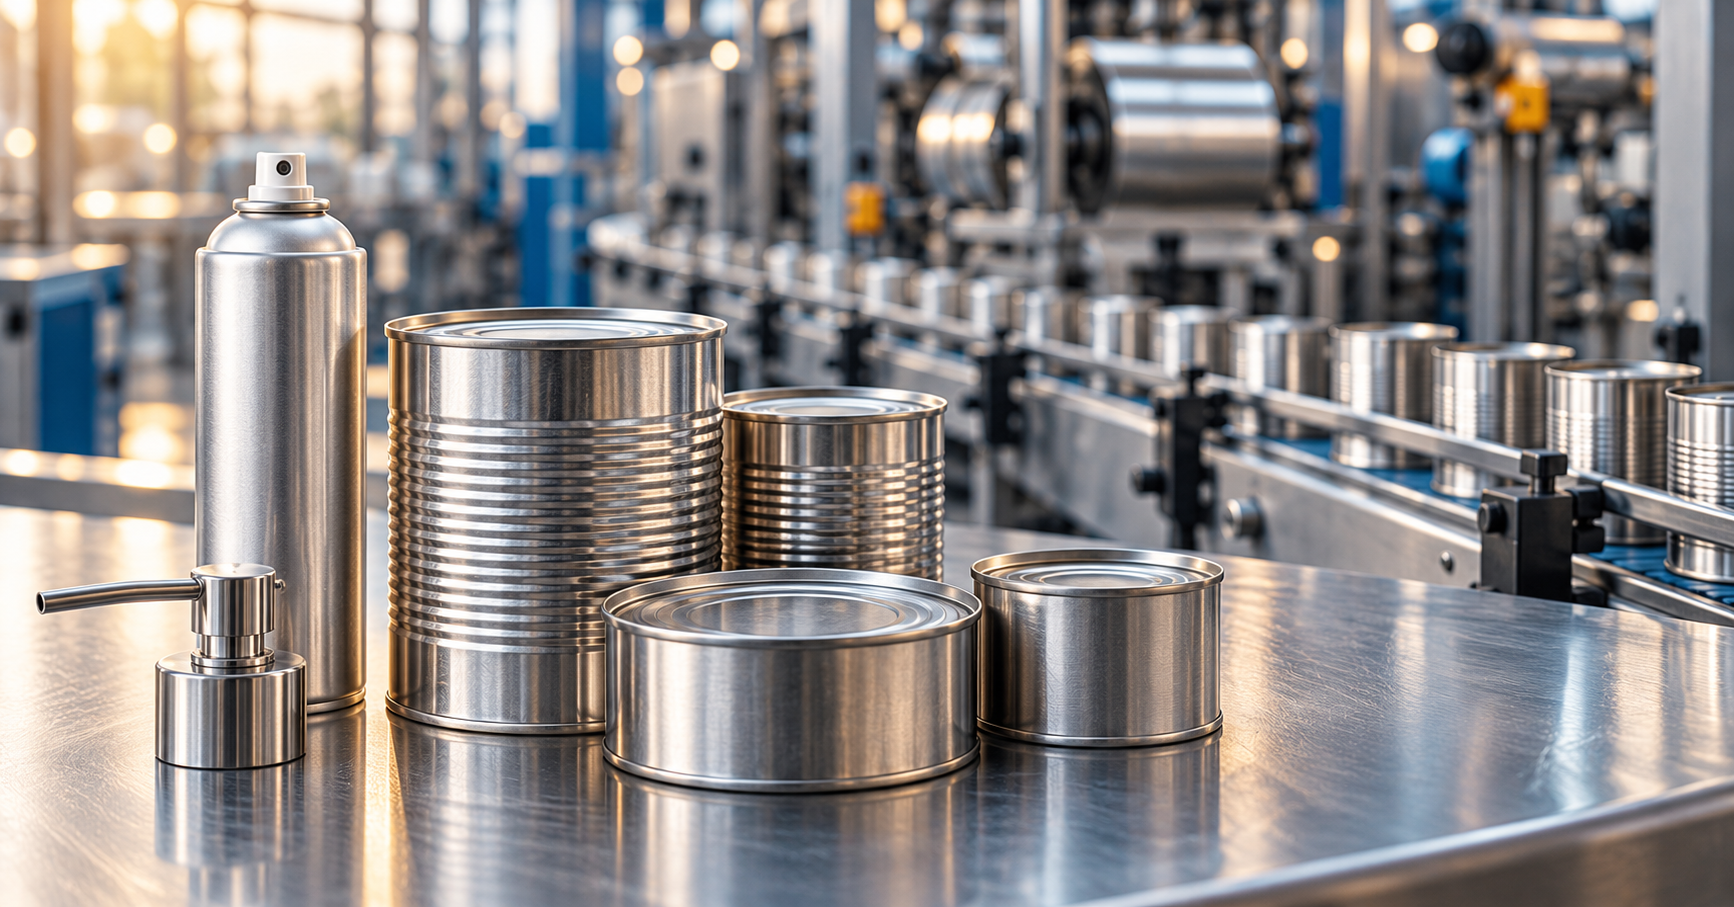
Silgan earns revenue by supplying packaging to consumer-product manufacturers. Its products include containers for pet and human food, closures for food and beverages, and dispensing systems used in applications such as fragrance and personal care. These businesses combine manufacturing scale with customer-specific requirements for product protection, compatibility and reliable supply.
Trivium supplies metal cans and aerosol containers used in food, seafood, pet food, nutrition, beauty and personal care. It recorded approximately $3 billion of revenue in 2025. Its product overlap gives the combination a direct operating connection: purchasing, production and customer requirements involve related materials and manufacturing capabilities.
The target also brings an international network. According to Ontario Teachers’ Pension Plan’s sale announcement, Trivium serves more than 800 customers and operates 57 locations across 18 countries. Ontario Teachers’ will fully exit its investment. The breadth of the acquired network offers opportunities to coordinate supply, while increasing the number of facilities and customer relationships involved in integration.
Manufacturing scale creates value when purchasing terms, plant utilization and production efficiency improve without disrupting service. A larger footprint can support those improvements, but decisions about sourcing and production must accommodate the specifications and delivery requirements of existing customers.
How Silgan receives cash and retains control
The transaction presentation shows the proposed funding structure:
| Sources of funding | US$ billion |
|---|---|
| New Silgan MCC debt | 4.9 |
| Silgan’s retained equity contribution | 1.5 |
| AIP cash equity | 1.0 |
| Total sources, including retained equity | 7.4 |
The equity arithmetic explains the ownership allocation. AIP’s approximately $1 billion investment for 40% implies approximately $2.5 billion of combined equity value; Silgan’s 60% corresponds to $1.5 billion. Adding its $2.3 billion cash receipt reconciles to the $3.8 billion assigned value of Silgan’s contributed businesses.
That cash release is supported by a recapitalization of the enlarged business. Silgan MCC would remain fully consolidated in Silgan’s accounts, so the subsidiary’s financing remains relevant when evaluating group leverage. The distribution changes where financial capacity sits within the organization; it also leaves AIP entitled to its share of future equity returns.
For existing shareholders, the useful comparison is the value of the cash released plus the retained interest against the earnings and ownership contributed. The receipt alone cannot establish whether the arrangement creates value. Future debt service, integration expenditure and distributions from the partnership will influence the cash ultimately available to Silgan.
The lower purchase multiple depends on a large earnings uplift
Trivium’s proposed enterprise value is approximately $3.4 billion. Silgan quotes a purchase multiple of 7.1 times trailing adjusted EBITDA, falling to 4.8 times after expected annual synergies of $225 million. Management expects those savings to build over three years.
AER’s reconciliation shows the scale of the assumption. Dividing $3.4 billion by the rounded 7.1-times multiple implies approximately $479 million of trailing adjusted EBITDA. The $225 million savings target equals roughly 47% of that earnings base. Adding it produces approximately $704 million, bringing the multiple to about 4.8 times.
These savings arise across the combination, so they should not be interpreted as a standalone Trivium margin forecast. Nevertheless, they account for a large part of the advertised improvement in acquisition economics. Adjusted EBITDA also precedes interest, tax and capital expenditure, leaving several steps between the projected savings and distributable cash.
Procurement improvements can benefit from combined purchasing volumes, while operational changes may require changes to equipment, staffing or production arrangements. The relevant evidence after closing will be savings achieved net of implementation costs, together with service performance and cash conversion. Those disclosures will show how much of the projected earnings uplift becomes an economic benefit for shareholders.
Existing earnings still need to support the transition
Silgan also maintained its third-quarter and full-year 2026 adjusted earnings outlook. The July results announcement set annual adjusted diluted EPS guidance at $3.73–$3.93, compared with $3.72 in 2025. First-half adjusted diluted EPS was $1.76, versus $1.83 a year earlier.
Simple subtraction, assuming broadly stable diluted share counts, implies approximately $1.97–$2.17 of second-half adjusted EPS to meet the annual range. The comparable 2025 second-half amount was approximately $1.89. That requires an improvement of roughly 4%–15%, with July’s third-quarter guidance of $1.21–$1.31 expected to provide much of the second-half contribution.
The near-term operating comparison therefore remains relevant while the acquisition awaits completion. Management’s forecasts use adjusted earnings, which exclude specified items, including acquired-intangible amortization and rationalization charges. They should remain separate from GAAP earnings and from the expected benefits of a transaction scheduled to close next year.
Closing terms and realized savings will determine the return
The proposed acquisition is expected to close in mid-2027, subject to regulatory approvals, works-council consultations and customary conditions. The sellers’ announcements confirm that these steps remain outstanding.
Silgan’s structure offers a credible way to enlarge its metal-packaging operation while releasing capital and preserving control. Its economic success depends on the price of that financing and the cash generated after integration. The final capitalization at closing, followed by evidence of savings and their implementation costs, will establish whether the retained interest and cash proceeds adequately compensate shareholders for the ownership contributed.
This material is provided for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security.
Companies Discussed
About AER Insights
Alliance Equity Research publishes timely insights on company-specific developments, industry trends, capital markets activity, and emerging investment themes across global public markets, with a particular focus on undercovered companies, sectors, and developments that often receive limited attention from mainstream financial research. Our analysis focuses on the financial, strategic, and valuation implications behind the headlines, using company disclosures, filings, market data, and sector context to help investors understand what matters, why it matters, and what to watch next.
Get AER Insights by Email
Receive new AER Insights and research updates in your inbox.
Related Insights
 Biotechnology & Healthcare
EyePoint’s Second Wet-AMD Failure Shifts Its Funding Priorities to Diabetic Eye Disease
EyePoint is cutting its workforce after DURAVYU missed another pivotal vision endpoint. Its diabetic macular edema program remains active, but the earlier supporting study differs materially from the ongoing trials. The investment assessment now depends on stronger clinical evidence and a clearer funding plan.
 Mining & Critical Minerals
Orezone’s Record Gold Output Leaves Higher Grades Central to Its Annual Outlook
Orezone’s two mines delivered record third-quarter production, but reaching annual guidance still requires a stronger finish. Completed waste stripping supports access to better ore. The longer-term opportunity at Casa Berardi also depends on sustained development spending, with its preliminary mine plan showing a gradual production ramp.
 Capital Markets & M&A
Proofpoint’s Varonis Acquisition Puts Data Access at the Center of Its AI Strategy
Proofpoint’s proposed $6.3 billion acquisition connects communications security with controls over sensitive enterprise data. Varonis brings growing cloud subscriptions, but migration inflates its headline growth rate. The purchase economics depend on stronger cash generation and commercial benefits that have yet to be quantified.
 Capital Markets & M&A
Transocean’s Larger Credit Line Links Financing Flexibility to the Valaris Merger
Transocean has retired expensive secured debt and arranged a larger revolving facility that depends on completing its Valaris acquisition. The developments improve its financing options, but lasting balance-sheet progress will depend on converting contracted drilling work into cash while absorbing the combined fleet.
About Alliance Equity Research
Alliance Equity Research publishes independent and company-sponsored equity research on undercovered, emerging, and high-potential public companies globally. Our analyst-built, model-backed research combines fundamental business analysis, financial forecasting, and valuation.
Email: info@alliancekp.com · Website: https://allianceequityresearch.com
For detailed company research, financial models, or coverage inquiries, contact our research team.
Research commentary for informational purposes. This document does not constitute personalized investment advice or a Buy, Hold, or Sell recommendation. For important disclosures, including information about research sponsorship and potential conflicts of interest, visit allianceequityresearch.com/disclosures.