 Alliance Equity Research
Cornish Metals’ £135 Million Raise Would Unlock South Crofty Funding at a Dilutive Price
Cornish Metals has proposed the equity financing needed to advance South Crofty and release its escrowed bond funding. The package also converts shareholder loans and introduces Glencore as a buyer of future production. Existing shareholders gain a clearer construction path while sharing the eventual returns across substantially more shares.
A financing proposal changes the investment assessment
Cornish Metals’ October 20 financing announcement creates a credible route through the funding constraint identified in AER’s September coverage. The proposed £135 million package would satisfy an important condition for releasing the company’s escrowed bond proceeds. Completion remains conditional.
The economic trade-off is clearer now. Financing would allow the developer to commit more confidently to construction toward targeted first production in mid-2028. Existing shareholders would own a smaller proportion of that funded project unless they invest additional capital. The investment assessment therefore depends on what the money delivers, the debt that future production must service and the ownership retained after financing.
South Crofty must turn underground ore into saleable concentrate
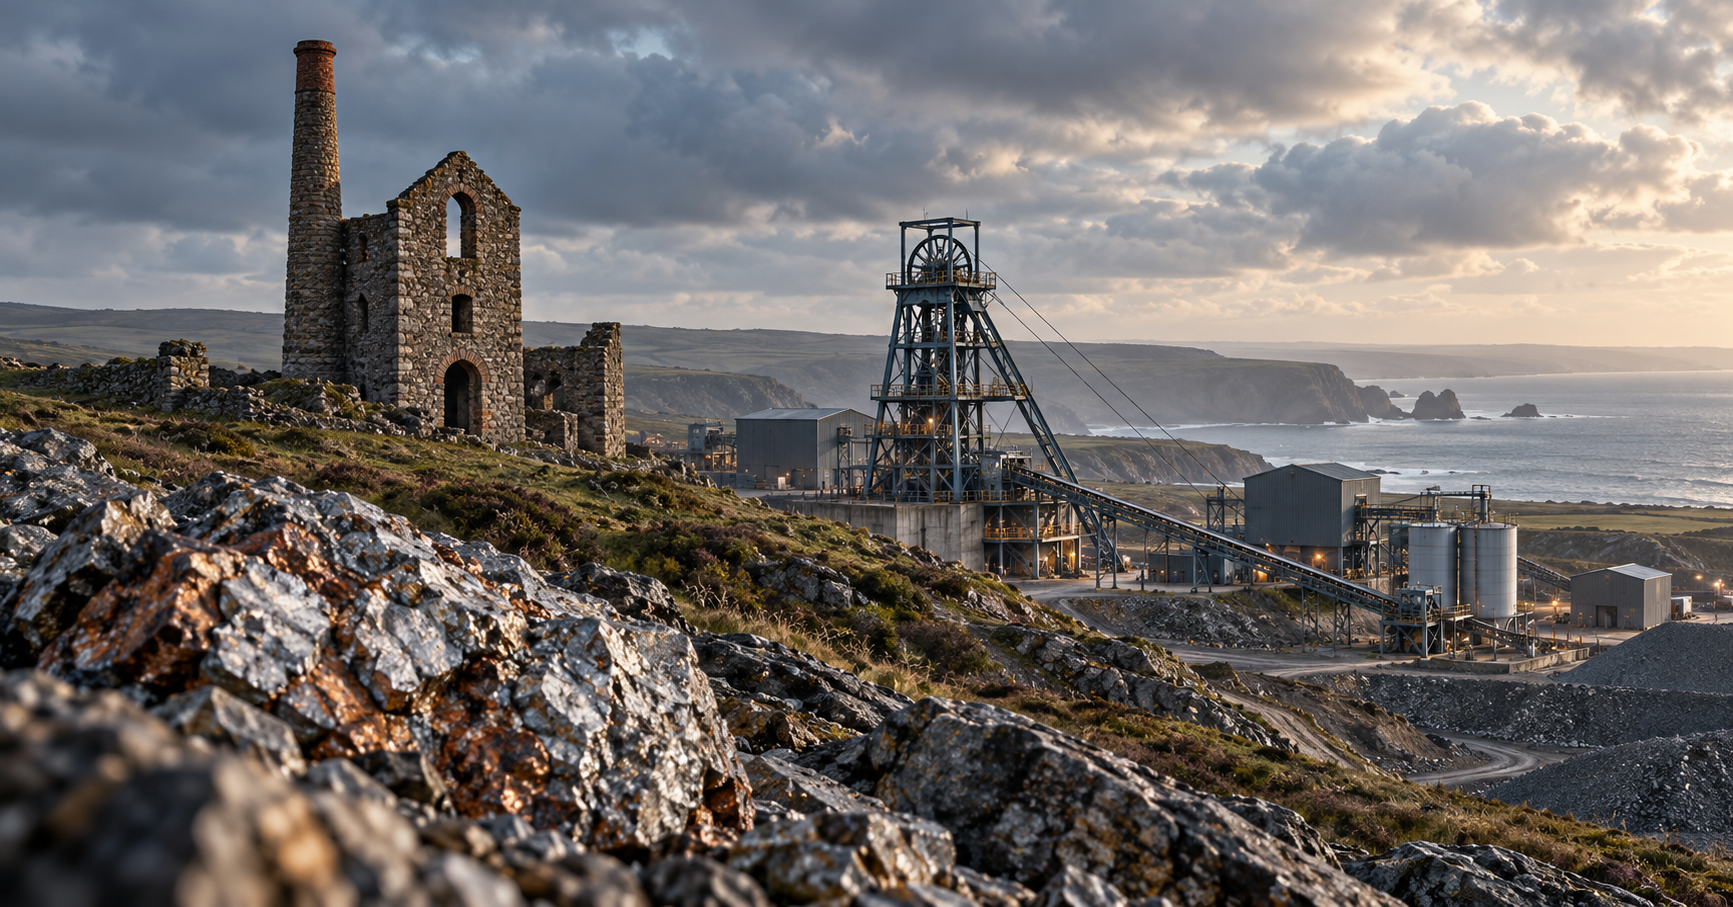
Cornish Metals owns South Crofty, an underground tin redevelopment in Cornwall. Tin’s use in electronics and electrical infrastructure gives the project strategic relevance, but its commercial returns will come from extracting and processing mineralised rock reliably. The company’s operating update describes an initial 14-year mine plan, targeting approximately 4,700 tonnes of annual tin-in-concentrate production during the first five years of full production. First production is targeted for mid-2028, leaving a construction period before concentrate sales begin.
The updated preliminary economic assessment envisages mining about 500,000 tonnes of material annually. Ore sorting would remove lower-value material before approximately half that volume enters the concentrator, increasing the tin grade of the material processed. The resulting concentrate is an intermediate product for subsequent smelting.
This makes recovery, sorting performance and plant availability consequential. Rejecting waste early can reduce the processing burden, but losing tin during sorting would reduce saleable output. Financing enables the equipment and underground development needed to deliver that operating system.
The updated preliminary economic assessment estimated £198 million of pre-production capital, a £180 million after-tax project net present value at a 6% real discount rate and a 20% internal rate of return. It modeled average annual after-tax cash flow of approximately £57 million in years two through six. These are preliminary project estimates, based on the study’s commodity-price and operating assumptions, and include Inferred Mineral Resources that have not been established as reserves. The project NPV is not an equity valuation after the proposed financing. Financing costs and the enlarged share count must be considered separately when assessing returns to shareholders.
Separate construction cash from debt conversion
The proposed £135 million equity package comprises approximately £80 million of fresh cash before expenses and £55 million of shareholder-loan principal and accrued interest exchanged for shares through subscription set-offs. The company’s £302 million financing and capitalisation plan therefore includes both cash and a noncash conversion. The conversion removes a repayment obligation; it does not put another £55 million into the bank.
| Financing and capitalisation sources | £ million | Allocation | £ million |
|---|---|---|---|
| Existing cash, rounded | 12 | South Crofty capital expenditure | 185 |
| Equity: approximately £80m cash plus £55m debt conversion | 135 | Shareholder loans and interest converted to equity (noncash) | 55 |
| Nordic bond funding | 155 | Bond interest during construction and ramp-up | 32 |
| Corporate costs and financing fees | 12 | ||
| Working capital and growth | Up to 10 | ||
| Additional cash requirement (purpose not further specified) | 8 | ||
| Total | 302 | Total at the stated upper allocation | 302 |
After excluding the £55 million conversion from both sides, AER calculates approximately £247 million of cash funding and allocations. Of this, £185 million is earmarked for South Crofty capital expenditure and £32 million for bond interest during construction and ramp-up. The balance covers corporate costs and fees, working capital and growth, and an £8 million cash requirement whose purpose the announcement does not further specify. That last amount cannot be assumed to be an additional construction contingency.
The interim accounts explain why the conversion matters. The shareholder facilities carried 13% interest, capitalised daily, and were repayable shortly after a qualifying equity raise. Converting them would reduce the cash that otherwise needed to leave the business when new equity arrived.
The bonds carry a 13.5% annual coupon, according to the interim accounts. A delay beyond the targeted mid-2028 first production would postpone revenue while extending the period of financing costs before the mine generates cash. The £185 million current construction allocation and the PEA’s £198 million pre-production estimate also have different reference points: work has continued since the study. The smaller current allocation should not be described as a demonstrated cost saving without a reconciled remaining-cost schedule.
The issue price determines how much ownership changes hands
The separate retail-offer announcement sets a 60p subscription price, a 41.2% discount to the October 13 closing mid-price. That reference predates the voluntary trading pause used for the financing.
At 60p, £135 million corresponds to approximately 225 million new shares, calculated by dividing the proposed subscription amount by the issue price. The interim accounts reported 125.47 million ordinary shares outstanding at June 30. Using that dated base and the proposed issuance alone gives an illustrative total of 350.47 million shares: existing shares would represent approximately 35.8% of the enlarged count. A nonparticipating holder’s proportional ownership would fall by approximately 64.2%. This is ownership dilution, not a forecast of the financial loss on the holding.
This illustration excludes changes in shares since June, options and other transaction-related issuance, including shares due for deferred acquisition consideration when the final investment decision becomes effective. The final ownership calculation requires those items and the completed allocations. The dilution is substantial, but its effect on investment value also depends on whether financing makes a commercially productive mine achievable.
Glencore connects funding with a commercial outlet
Glencore has conditionally committed approximately £11.2 million and agreed to purchase all South Crofty tin concentrate for six years from commercial production. Detailed pricing terms were not disclosed.
A contracted buyer helps organise the route from concentrate production to sales. It does not establish the margin retained by the mine: payable metal, treatment terms, deductions and delivery costs influence the cash received. The agreement strengthens commercial visibility, while the absence of detailed terms limits any estimate of its incremental profitability.
Funding completion must precede the construction return
The proposed package improves the route to construction by replacing short-term shareholder debt with equity and providing cash alongside the existing bond financing. For a nonparticipating shareholder, the trade-off is a much smaller ownership percentage in a business with a more credible path to production. The prospective benefit rests on the mine generating cash after operating costs, continuing investment and debt service.
The announced timetable envisages a shareholder meeting on or around November 9 and admission of the new shares on November 10, subject to the stated conditions and permitted extensions. The bond’s equity-funding deadline is November 21, 2026, unless extended with bondholder consent. The company says the proposed raise would satisfy that equity condition; release of escrowed funds also requires the other conditions precedent. The fundraising components are interdependent and the placing is not underwritten.
Completing the raise and releasing the bond cash would reduce the immediate financing risk. Remaining planning, environmental and other consents must also be secured ahead of production. Thereafter, delivering the funded work toward mid-2028 without additional capital needs would preserve more of the modeled project returns for the enlarged shareholder base. A delay or funding shortfall would erode that benefit through further interest costs or another equity issuance.
This material is provided for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security.
Companies Discussed
About AER Insights
Alliance Equity Research publishes timely insights on company-specific developments, industry trends, capital markets activity, and emerging investment themes across global public markets, with a particular focus on undercovered companies, sectors, and developments that often receive limited attention from mainstream financial research. Our analysis focuses on the financial, strategic, and valuation implications behind the headlines, using company disclosures, filings, market data, and sector context to help investors understand what matters, why it matters, and what to watch next.
Get AER Insights by Email
Receive new AER Insights and research updates in your inbox.
Related Insights
 Industrials & Aerospace
GE Aerospace Raises Its Outlook as Maintenance Growth Supports Commercial Earnings
GE Aerospace’s higher annual guidance reflects stronger commercial services growth and a smaller expected GE9X earnings impact. Maintenance volume and pricing lifted commercial profit at a broadly stable margin. The remaining cash target implies faster year-over-year growth than GE delivered in the first nine months.
 Capital Markets & M&A
Silgan’s Trivium Deal Pairs a Cash Release With a Demanding Synergy Plan
Silgan’s proposed Trivium combination would release $2.3 billion in cash and preserve majority ownership of an enlarged metal-packaging business. Its $225 million savings target represents approximately 24% of combined pre-synergy adjusted EBITDA, making integration central to the economics and the intended eventual separation.
 Mining & Critical Minerals
Orezone’s Record Gold Output Leaves Higher Grades Central to Its Annual Outlook
Orezone’s two mines delivered record third-quarter production, but reaching annual guidance still requires a stronger finish. Completed waste stripping supports access to better ore. The longer-term opportunity at Casa Berardi also depends on sustained development spending, with its preliminary mine plan showing a gradual production ramp.
 Mining & Critical Minerals
NioCorp’s Elk Creek Funding Case Extends Beyond Its New Ferroniobium Purchase Commitment
NioCorp has disclosed $405.1 million of cash and secured a longer ferroniobium purchase commitment. Financing its Nebraska project also depends on the commercial prospects of scandium, titanium and rare earths, which supply approximately 74% of modeled lifetime revenue and carry different sales arrangements.
About Alliance Equity Research
Alliance Equity Research publishes independent and company-sponsored equity research on undercovered, emerging, and high-potential public companies globally. Our analyst-built, model-backed research combines fundamental business analysis, financial forecasting, and valuation.
Email: info@alliancekp.com · Website: https://allianceequityresearch.com
For detailed company research, financial models, or coverage inquiries, contact our research team.
Research commentary for informational purposes. This document does not constitute personalized investment advice or a Buy, Hold, or Sell recommendation. For important disclosures, including information about research sponsorship and potential conflicts of interest, visit allianceequityresearch.com/disclosures.