Transocean’s Larger Credit Line Links Financing Flexibility to the Valaris Merger
Transocean has retired expensive secured debt and arranged a larger revolving facility that depends on completing its Valaris acquisition. The developments improve its financing options, but lasting balance-sheet progress will depend on converting contracted drilling work into cash while absorbing the combined fleet.
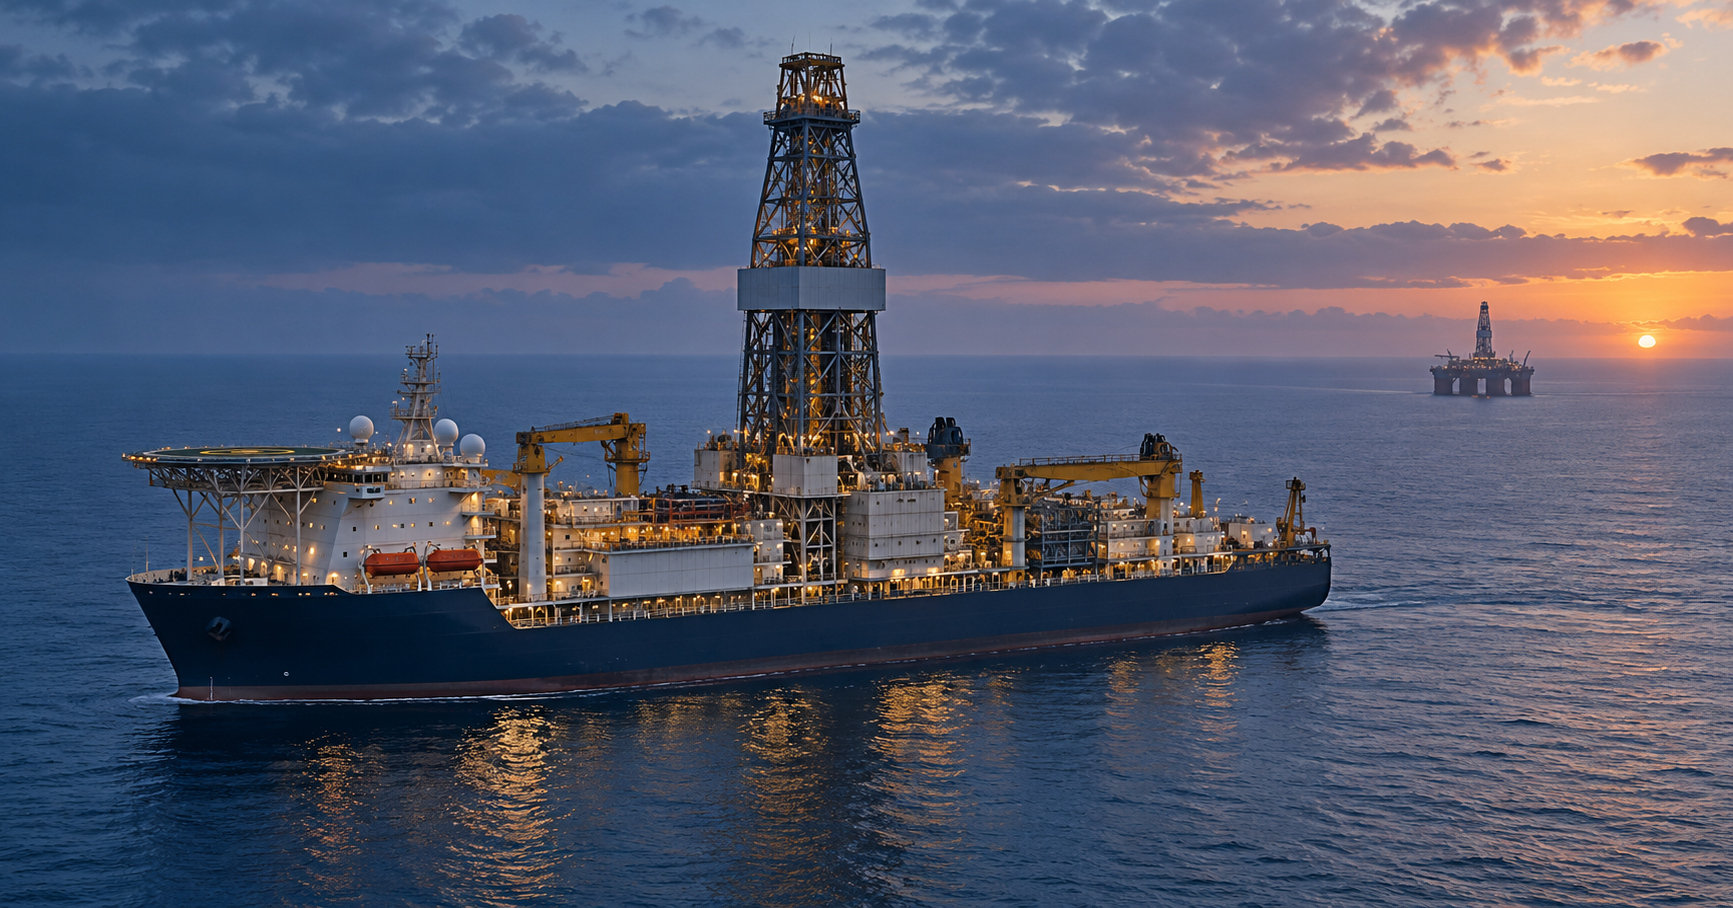
More borrowing capacity, alongside a completed repayment
Transocean’s October 15 financing announcement combines two developments with different timing. It has already retired $165 million of secured notes. A separate agreement would increase revolving credit commitments from $510 million to $750 million and extend their scheduled maturity from June 2028 to October 2031, subject to the Valaris acquisition closing and customary conditions.
Transocean supplies offshore drilling rigs and operating services to oil and gas producers. Its customers pay for drilling capacity under contracts, while Transocean carries the costs of crews, maintenance and keeping vessels available for work. Its focus on deepwater and harsh-environment operations makes reliable equipment and contract continuity central to cash generation.
The distinction between the financing measures is economically useful. Repaying the notes reduces future interest costs, while the expanded revolver would provide more flexibility to manage expenditure and customer receipts after the Valaris acquisition closes.
Debt retirement consumes cash before it saves interest
The October 15 SEC filing confirms that the 8% Deepwater Aquila notes, due in 2028, were retired on October 1. Transocean used cash on hand and the associated debt-service reserve to settle principal, a call premium and accrued interest. Management estimates approximately $22 million of interest-expense savings through maturity.
That estimate spans the remaining life of the notes. The simple annual coupon on $165 million at 8% is $13.2 million, before allowing for the original repayment schedule. The disclosed $22 million also needs to be considered alongside the redemption premium and the earnings forgone on cash used.
AER’s interpretation is that this improves future financing costs while using liquidity immediately. Gross debt falls by the principal repaid, but the simultaneous reduction in cash means the repayment alone cannot establish an equivalent improvement in net debt. The reserve-account component also requires care when comparing unrestricted liquidity before and after redemption.
The credit agreement preserves lender protections
The larger revolver adds $240 million of commitments, a calculated increase of 47.1%. Its significance depends on the borrowing conditions as well as its size: the facility remains secured, and its contractual covenants include minimum available liquidity of $200 million and a maximum debt-to-tangible-capitalization ratio of 60%. Both measures use the agreement’s definitions.
Collateral coverage must be at least 2.5 times revolving commitments at the specified quarterly measurement dates. At $750 million of commitments, that corresponds to $1.875 billion of collateral rig value under the contractual methodology, calculated as $750 million multiplied by 2.5. This is a requirement against the pledged assets, not an appraisal of the whole company.
These provisions connect access to credit with asset values and financial capacity. A longer maturity gives management more time, but lenders retain protection if liquidity or collateral coverage deteriorates. For equity holders, the practical improvement is a longer financing window within which operating cash flow can support debt reduction.
Merger progress changes the timing of that flexibility
Valaris disclosed on October 14 that Brazil’s competition authority, CADE, had approved the combination without restrictions. The decision was expected to be published on October 15 or 16, starting a 15-day waiting period. Once final, it would satisfy all regulatory approval conditions; other closing conditions would remain. The companies continued to anticipate completion in the fourth quarter.
The acquisition would broaden Transocean’s exposure across offshore drilling markets. Valaris brings deepwater assets and jackup expertise, extending the combined business into shallow-water operations. In the February transaction announcement, management identified more than $200 million of incremental cost synergies, separate from Transocean’s existing cost-reduction programme. Those remain management expectations whose delivery depends on integration.
Valaris shareholders are to receive 15.235 Transocean shares for each Valaris share. The approximately $5.8 billion announced transaction value was based on historical share prices; a fixed exchange ratio leaves the consideration’s dollar value exposed to Transocean’s share price. The roughly $17 billion enterprise value cited at announcement described the combined business. Neither figure is a current valuation quotation.
Operating cash flow remains the source of durable debt reduction
Transocean’s second-quarter results reported $236 million of operating cash flow and $24 million of capital expenditure, producing $212 million of free cash flow. Quarter-end debt principal remained $5.107 billion. Cash generation therefore provides useful repayment capacity, although the balance-sheet task extends beyond the Aquila redemption.
The same release permits the following reconciliation of its standalone revenue outlook:
| Contract drilling revenue | $ million |
|---|---|
| First-half actual: $1,081 million + $966 million | 2,047 |
| Full-year guidance issued August 5 | 3,900–3,975 |
| Implied second-half requirement | 1,853–1,928 |
| Third-quarter guidance issued August 5 | 920–960 |
| Implied fourth-quarter range using those endpoints | 893–1,008 |
AER calculations from the linked results and guidance. The fourth-quarter range combines opposite endpoints of the annual and third-quarter ranges.
At the guidance midpoints, fourth-quarter revenue would be $950.5 million, close to the third-quarter midpoint of $940 million. That outlook implies broadly stable quarterly revenue, following the second-quarter utilization decline. It provides no basis for assuming a sharp near-term acceleration, and acquisition consolidation could change the eventual reporting scope.
Contract approvals improve visibility, with cash arriving through operations
Shell’s $62 million award extends Transocean Norge’s scheduled work in Norway, with operations expected to continue directly from its existing programmes. The larger development was final approval of approximately $1 billion of previously announced Equinor work, which converted that amount into firm backlog.
Backlog supports planning because it identifies contracted future revenue. Cash still arrives as work is performed, with maintenance, downtime and contract costs affecting the amount retained. AER’s assessment is that the financing arrangements give Transocean more room to manage those operating demands; the contracted fleet must supply the cash that makes lower debt sustainable.
The next scheduled evidence is third-quarter earnings and a fleet status report on November 2, followed by the conference call on November 3. The relevant disclosures will be cash generation, spending requirements, contract commencement timing and the remaining acquisition conditions. Because the Aquila redemption occurred on October 1, its cash settlement falls after the September quarter-end.
This material is provided for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security.
About AER Insights
Alliance Equity Research publishes timely insights on company-specific developments, industry trends, capital markets activity, and emerging investment themes across global public markets, with a particular focus on undercovered companies, sectors, and developments that often receive limited attention from mainstream financial research. Our analysis focuses on the financial, strategic, and valuation implications behind the headlines, using company disclosures, filings, market data, and sector context to help investors understand what matters, why it matters, and what to watch next.
Get AER Insights by Email
Receive new AER Insights and research updates in your inbox.
Related Insights
 Industrials & Aerospace
Schneider’s Data-Center Growth Supports a Software Expansion With Demanding Acquisition Economics
Schneider Electric has raised its outlook again as demand for data-center power and cooling equipment strengthens. Its proposed PTC acquisition would extend the business into product engineering software, but the purchase economics depend on earnings benefits that exceed the identified cost savings.
 Mining & Critical Minerals
Atalaya’s Copper Recovery Improves as Fresh Equity Funds Its Next Growth Phase
Atalaya is extracting more copper from each tonne processed at Riotinto, supporting output without another large plant expansion. Its stronger balance sheet also reflects January’s equity raise and lower borrowings. Future returns depend on turning that funding into accessible ore and reliable processing performance.
 Capital Markets & M&A
CCC’s $6.1 Billion Buyout Puts a Price on Embedded Insurance Software
GTCR and Elliott’s proposed acquisition of CCC Intelligent Solutions values the business at approximately 12.5 times its July forecast for 2026 adjusted EBITDA. Its position connecting insurers and repair shops supports the investment case, while cash conversion and AI monetisation will determine the buyers’ returns.
 Capital Markets & M&A
Schneider’s $23.7 Billion PTC Deal Needs More Than Cost Savings
Schneider Electric is paying a 42.3% premium for PTC and funding most of the purchase with debt. The advertised valuation falls from 21 times to 13 times 2027 adjusted EBITA only after a demanding combination of cost savings and commercial synergies.