 Alliance Equity Research
Hudbay Approves Copper World as Partner Funding Cushions a Larger Capital Commitment
Copper World’s construction approval gives Hudbay a defined route to a new U.S. mine. Partner capital and planned borrowing defer its cash contributions, but the revised study increases the commitment and makes later expansion spending central to the expected production gains.
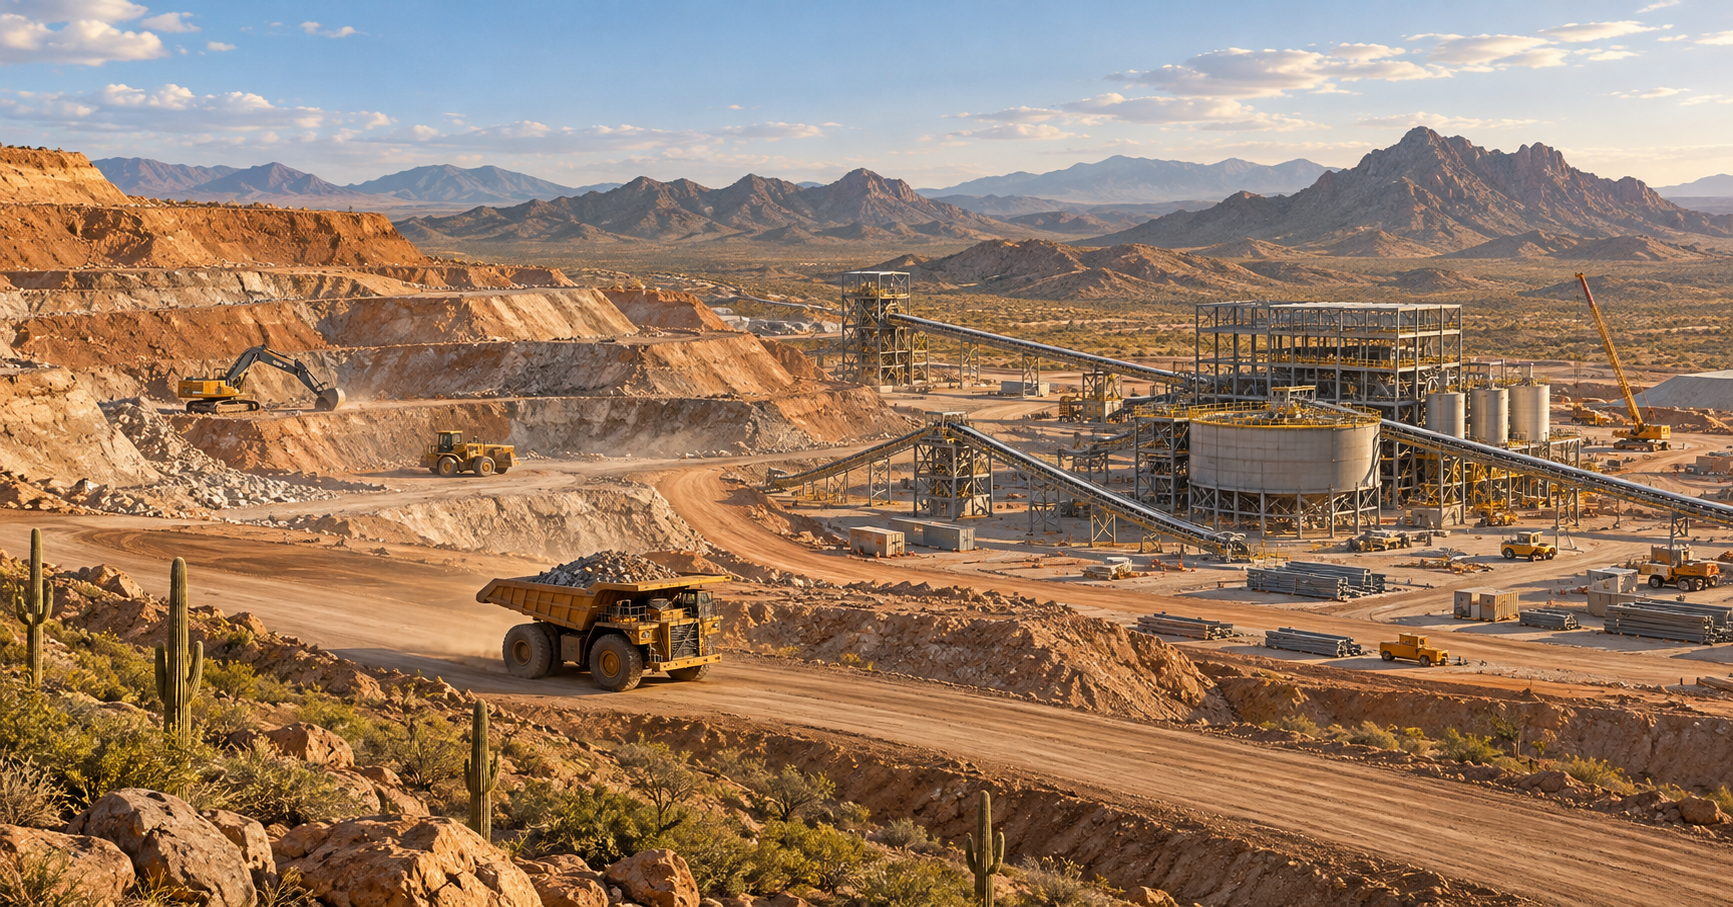
Hudbay Minerals and Mitsubishi approved construction of Copper World on October 21, moving the Arizona copper project from feasibility work into a construction programme with first production targeted for the second half of 2029. Partner funding makes the development more manageable for Hudbay, although its larger capital commitment and later expansion spending reduce financial flexibility during development. All major permits for initial development and operation have been secured.
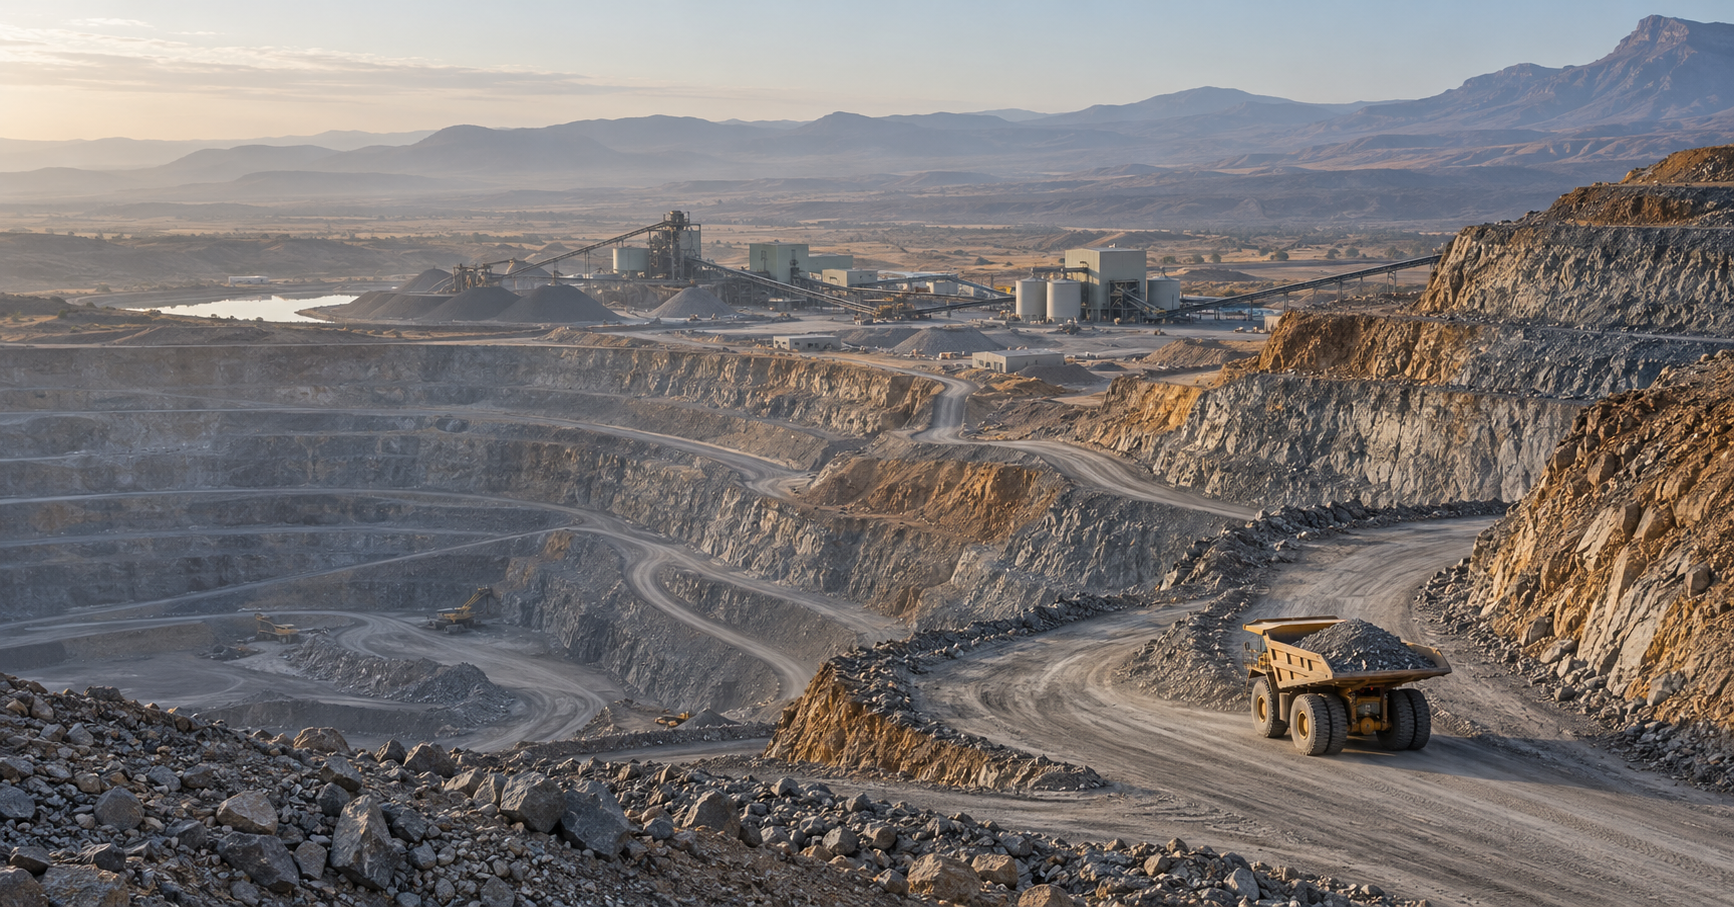
Hudbay Minerals (TSX/NYSE: HBM) already operates mines in Peru and Canada, selling copper and other metals. Hudbay owns 70% of Copper World LLC; Mitsubishi Corporation, the Japanese trading and investment group, owns 30%. The planned open-pit mine would produce copper concentrate, a mineral-rich intermediate sold for further smelting and refining, plus molybdenum concentrate. A separate facility to produce refined copper cathode remains an option.
Hudbay’s remaining contribution has increased
The earlier financing plan put Hudbay’s remaining equity contribution at approximately $200 million, based on the 2023 pre-feasibility study. That estimate was still cited when the Mitsubishi investment closed in January. Hudbay now expects approximately $500 million, with its first contribution still deferred until 2028. The timing benefit survives, but the amount that existing operations must help finance has increased.
The 2023 study estimated initial growth capital of $1.323 billion. The new estimate is $2.07 billion in 2026 dollars, including about $200 million for scope changes. Hudbay had previously warned of both cost inflation and changes intended to accommodate future expansion. Differences in equipment financing and project design prevent treating the increase as a pure construction-cost inflation measure.
Construction approval raises Copper World’s 2026 growth-capital forecast from $135 million before sanctioning to $245 million, adding $110 million of fourth-quarter development expenditure. These are expenditures at the joint venture, which its initial partner capital helps fund before Hudbay’s later equity contributions.
Partner capital and borrowing meet different needs
Mitsubishi contributed approximately $420 million to Copper World LLC at January’s closing and committed a further $180 million within 18 months. The money finances studies, pre-construction work and development. Mitsubishi must also fund 30% of subsequent equity contributions. Hudbay therefore retains a majority economic interest while sharing both future funding obligations and the project’s returns with its partner.
Wheaton Precious Metals supplies upfront funding in exchange for future precious-metal deliveries. Hudbay’s October 21 announcement expected the $230 million stream deposit within the first four months after the investment decision. Under the amended stream terms, ongoing payments for gold and silver are 15% of spot prices, with a further $70 million deposit contingent on mill expansion. This arrangement brings forward part of the value of future by-product production to help pay for construction.
| Hudbay’s illustrative funding bridge | US$ million |
|---|---|
| Initial growth capital, net of equipment financing | 2,070 |
| 2026 study and pre-sanction expenditure | 135 |
| Total uses in the illustration | 2,205 |
| Less: Mitsubishi initial investment | (600) |
| Less: Wheaton initial stream deposit | (230) |
| Less: anticipated project debt | (650) |
| Remaining equity funding requirement | 725 |
The remaining $725 million is the combined equity requirement for both owners, shared in their 70%/30% proportions. Hudbay presents its own contribution at approximately $500 million. This funding mix assumes that the joint venture secures the planned $650 million of project debt, which had not been announced as closed with the construction decision. A borrowing shortfall would require replacement funding and could increase the owners’ cash contributions.
Reported cash includes money reserved for the project
Hudbay’s June-quarter financial disclosure reported $890.9 million of cash and equivalents at June 30, including $334.5 million held by Copper World LLC and contractually reserved for that project. A separate $49.8 million of unspent municipal-bond proceeds was classified as restricted cash, outside the $890.9 million balance. Mitsubishi’s initial contribution had already entered the consolidated accounts, so these cash balances include the remaining partner-funded project money.
Hudbay reported $204.7 million of company-defined free cash flow in the first half of 2026. The measure adjusts operating cash flow for working-capital movements and deducts sustaining capital expenditure and specified operating-site lease, equipment-financing and community payments. It is calculated before growth capital expenditure. That cash generation supports further investment, but Copper World, the New Ingerbelle expansion at Copper Mountain and the Cactus copper-development project in Arizona all require growth funding from the wider capital budget.
Hudbay also plans to increase its corporate revolving facilities from $450 million to $700 million and extend maturity from November 2028 to November 2030, with closing expected in the fourth quarter. The facilities provide borrowing capacity to support development and manage the maturity of its 2029 notes. They are separate from the proposed Copper World project debt.
Higher output requires another round of investment
Copper World’s expected first-decade production averages 102,000 tonnes annually, compared with Hudbay’s 2026 consolidated guidance of 110,000–138,000 tonnes. The proposed mine is therefore large relative to the existing business, although its output is quoted on a 100% project basis and Hudbay retains a 70% economic interest.
The study projects first-decade cash costs of $1.65 per pound of copper and sustaining cash costs of $2.22 per pound, both after credits for other metals produced. The broader sustaining measure includes sustaining capital expenditure, royalties and equipment-financing payments. Against the study’s $5.00/lb long-term copper assumption, this cost profile supports the mine’s potential to generate cash for further investment.
Output rises from an average 84,000 tonnes annually in years one to five to 120,000 tonnes in years six to ten. The post-startup investment programme includes a $25 million molybdenum plant in operating year one, a $242 million crushing-and-conveying system in year three and a $443 million concentrator expansion in year four. Together, these growth projects require a further $710 million. The conveyor system would reduce truck haulage as the mine supplies more ore to the expanded processing plant.
Management expects retained operating cash to fund the later work, supplemented by the contingent stream payment. Cash retained for expansion is unavailable for distribution during that period. The initial $2.07 billion estimate also already deducts $127 million of anticipated equipment financing, whose repayments enter operating-period cash requirements. Expansion estimates include work at pre-feasibility level, and permit amendments are still required for the expansion projects.
Copper prices still govern asset returns
Hudbay estimates a 32% levered internal rate of return on its investment under the financing plan. The base-case project return before the proposed project borrowing is 16.8%; it already incorporates the stream and equipment-financing assumptions. Partner funding and debt reduce and defer Hudbay’s own cash outlay, improving the modelled return on that investment. Cash can be distributed to the owners after meeting operating costs, reinvestment, taxes and debt-service requirements.
| Long-term copper-price scenario | Whole-project after-tax NPV at 8% | Project IRR |
|---|---|---|
| $4.50/lb | $663 million | 12.9% |
| $5.00/lb base case | $1,241 million | 16.8% |
| $6.00/lb | $2,258 million | 22.5% |
AER calculates that the $4.50/lb scenario’s project value is approximately 47% below the $5.00/lb base case, using the disclosed net present values of $663 million and $1,241 million. This sensitivity shows how lower copper revenue can erode the value remaining after the construction investment. Lower copper prices would also reduce the operating cash available for expansion and debt service, potentially delaying distributions or requiring further funding.
The sanctioned base case has a 15-year mine life. The separate 37-year extension requires federal permits to expand onto federal land; it is not secured by the permits for initial operations. The investment assessment is therefore strongest when anchored in the initial mine and its scheduled expansion, with additional life treated as contingent upside.
Partner capital makes Copper World’s construction more manageable for Hudbay and supports a material increase in copper production. The higher contribution now expected from Hudbay and the need to retain operating cash for expansion make the project a larger commitment of future financial capacity. Securing the planned $650 million of project debt would support the deferred equity schedule ahead of first production targeted for the second half of 2029. After startup, copper prices and the mine’s ability to finance the $710 million expansion programme from retained cash will determine how much of its operating benefit becomes available to its owners. A financing gap or weaker copper prices would increase cash requirements, delay expansion or reduce distributions.
This material is provided for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security.
Companies Discussed
About AER Insights
Alliance Equity Research publishes timely insights on company-specific developments, industry trends, capital markets activity, and emerging investment themes across global public markets, with a particular focus on undercovered companies, sectors, and developments that often receive limited attention from mainstream financial research. Our analysis focuses on the financial, strategic, and valuation implications behind the headlines, using company disclosures, filings, market data, and sector context to help investors understand what matters, why it matters, and what to watch next.
Get AER Insights by Email
Receive new AER Insights and research updates in your inbox.
Related Insights
 Capital Markets & M&A
LSEG’s Octus Deal Expands Credit Data at a Price That Requires Sustained Growth
The $3.535 billion acquisition adds recurring revenue from credit research, private loan documents and portfolio tools. LSEG gains a credible route into specialist customer workflows, but debt funding and an initially neutral adjusted earnings contribution leave sustained growth central to the return on its investment.
 Biotechnology & Healthcare
Helus Pharma Redesigns Its Anxiety Study as Pivotal Depression Data Approach
Helus is moving HLP004 into a larger, placebo-controlled monotherapy study while its lead depression drug approaches a Phase 3 readout. The revised anxiety program could establish a clearer efficacy signal, but near-term shareholder value depends more heavily on HLP003 and the cost of completing its development.
 Mining & Critical Minerals
Cornish Metals’ £135 Million Raise Would Unlock South Crofty Funding at a Dilutive Price
Cornish Metals has proposed the equity financing needed to advance South Crofty and release its escrowed bond funding. The package also converts shareholder loans and introduces Glencore as a buyer of future production. Existing shareholders gain a clearer construction path while sharing the eventual returns across substantially more shares.
 Mining & Critical Minerals
Orezone’s Record Gold Output Leaves Higher Grades Central to Its Annual Outlook
Orezone’s two mines delivered record third-quarter production, but reaching annual guidance still requires a stronger finish. Completed waste stripping supports access to better ore. The longer-term opportunity at Casa Berardi also depends on sustained development spending, with its preliminary mine plan showing a gradual production ramp.
About Alliance Equity Research
Alliance Equity Research publishes independent and company-sponsored equity research on undercovered, emerging, and high-potential public companies globally. Our analyst-built, model-backed research combines fundamental business analysis, financial forecasting, and valuation.
Email: info@alliancekp.com · Website: https://allianceequityresearch.com
For detailed company research, financial models, or coverage inquiries, contact our research team.
Research commentary for informational purposes. This document does not constitute personalized investment advice or a Buy, Hold, or Sell recommendation. For important disclosures, including information about research sponsorship and potential conflicts of interest, visit allianceequityresearch.com/disclosures.