 Alliance Equity Research
Critical Minerals Are Forcing Aerospace to Rethink Materials, but Substitution Has Limits
Aerospace suppliers are testing alternatives to rare-earth-dependent coatings as China’s dominance in critical-mineral production and processing keeps supply-chain risk elevated. Substitution can reduce exposure in selected applications, but it does not solve the wider problem of concentrated refining and component supply.
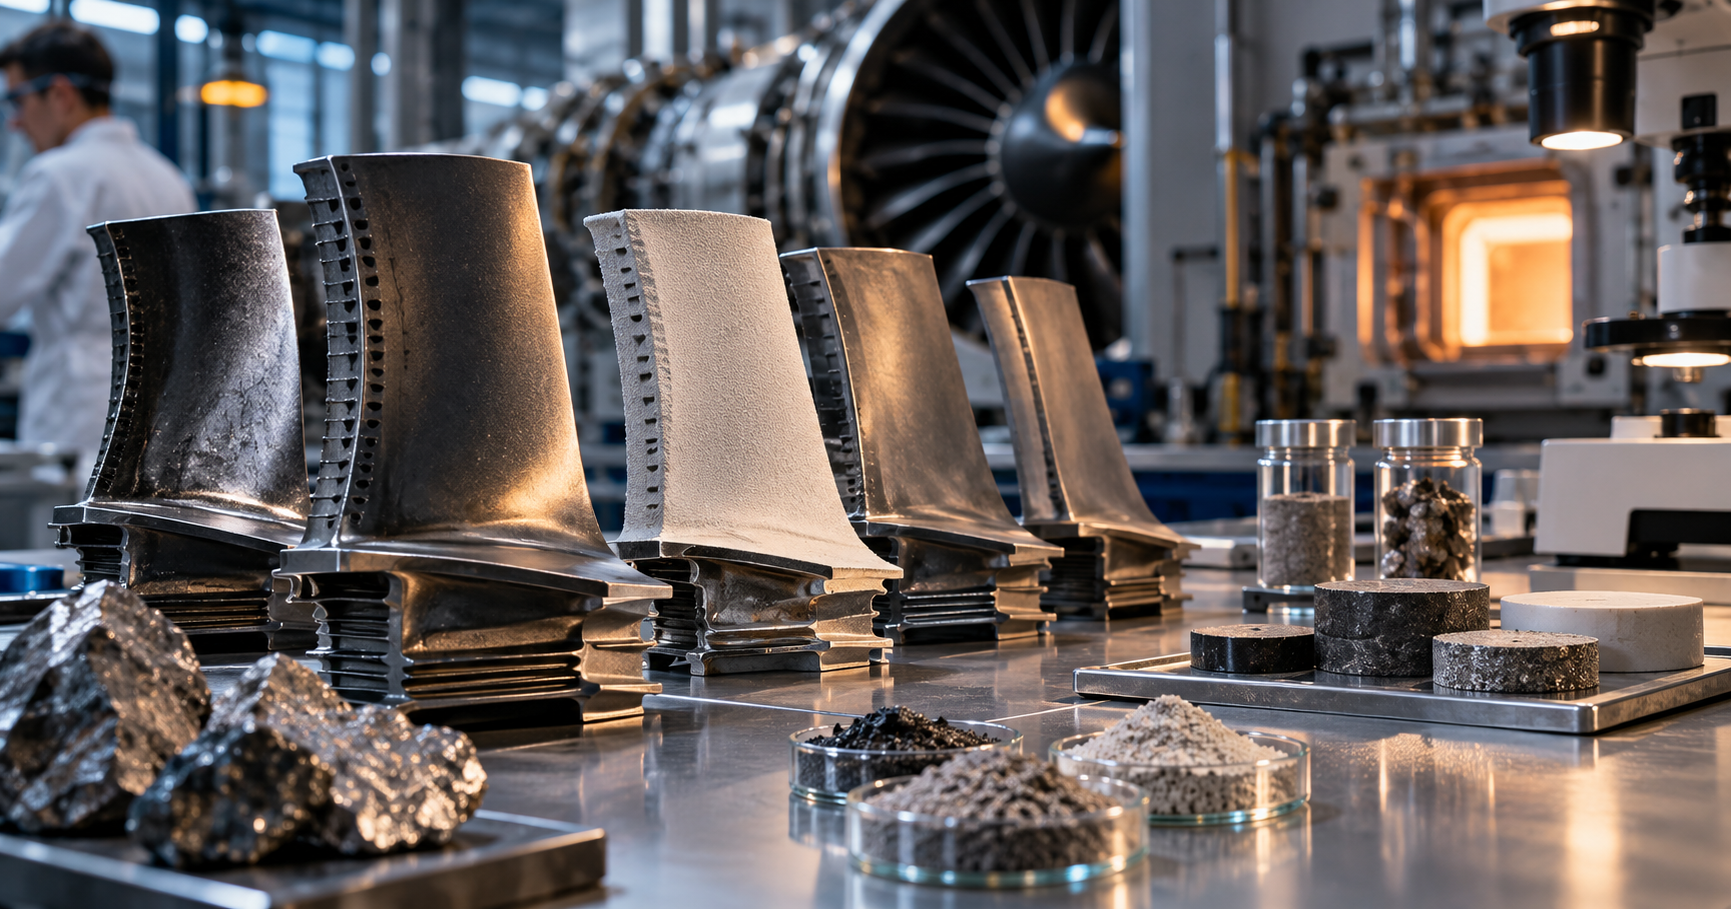
Rare earths and other critical minerals are usually discussed through the lens of electric vehicles, permanent magnets, semiconductors, and defense equipment. Aerospace is now providing another example of how concentrated mineral supply can affect product design itself.
Suppliers are revisiting older thermal-barrier coating technologies and alternative ceramic systems as access to materials such as yttrium becomes more difficult and expensive. Canada’s National Research Council is studying zirconium dioxide and other ceramic-oxide systems that were used decades ago, while Oerlikon Metco is developing coatings that reduce or eliminate rare-earth inputs.
This is an important shift.
Companies are not simply looking for another mine or another supplier. Some are trying to reduce the quantity of strategically exposed materials required in the final product.
That can lower mineral intensity over time, but aerospace qualification cycles are long and performance requirements are strict. In practice, substitution is likely to be gradual rather than immediate.
China Still Controls a Large Share of the Supply Chain
The scale of China’s position explains why manufacturers are looking at product-level alternatives.
China accounted for an estimated 82% of global mined tungsten production and 71% of mined rare-earth production in 2024. It also produced 99% of primary gallium, 88% of primary magnesium, 87% of silicon metal, 70% of refined indium, and 82% of natural graphite.
The concentration becomes even greater further downstream.
The International Energy Agency estimates that China represented approximately:
| Supply-chain stage | China share, 2024 |
|---|---|
| Magnet rare-earth mining | 60% |
| Rare-earth refining | 91% |
| Sintered permanent magnet production | 94% |
The 94% share in permanent magnets is particularly important because downstream manufacturing capability is harder to replicate quickly than mine supply alone.
The distinction matters for investors. A new mine can improve raw-material availability, but it does not immediately create separation, refining, alloying, magnet manufacturing, or aerospace-qualified component capacity.
Prices Show That Supply Risk Is Already Economic, Not Theoretical
The supply issue is visible in commodity pricing.
China domestic NdPr oxide, a major feedstock for NdFeB permanent magnets, was quoted at approximately RMB 738,000 per tonne on September 24, 2026, up from RMB 593,500 at the end of December 2025.
That represents an increase of roughly 24% in nine months.
Dysprosium oxide was quoted at RMB 1.435 million per tonne on the same date, while terbium oxide was around RMB 6.575 million per tonne. These heavier rare earths are used in high-performance magnet applications where temperature resistance and magnetic stability matter.
The pricing signal is not limited to rare earths.
Tungsten APT, the main intermediate benchmark used in the tungsten industry, was quoted at roughly $3,000 per metric tonne unit on a CIF Rotterdam basis in early September 2026.
That level is especially relevant because tungsten is used in high-temperature, high-density, cutting, aerospace, and defense applications, while China produces more than four-fifths of mined supply.
These prices do not prove that every downstream user is facing the same procurement cost. Export licensing, geography, contract terms, product purity, and inventory positions can produce large differences between domestic Chinese benchmarks and ex-China delivered prices.
But they do show that strategic-mineral supply risk is increasingly showing up in actual input costs.
Trade Data Also Points to Persistent Supply Friction
China’s rare-earth magnet exports to the United States fell to 512 tonnes in August 2026, down about 21% from July and roughly 13% from a year earlier.
That matters because permanent magnets are not just raw materials. They are already highly processed components used across motors, aerospace systems, electronics, industrial machinery, and defense equipment.
The data also highlight how sensitive supply remains to trade policy.
In July 2026, Chinese rare-earth magnet exports to the United States had risen sharply, including a 32.6% month-on-month increase according to Chinese customs data. By August, shipments had fallen again.
This volatility is one reason manufacturers are reconsidering how much strategic-mineral exposure they are willing to accept in product design.
Substitution Is Easier in Some Materials Than Others
Substitution is often discussed as though it is a binary question: either a mineral is essential or it can be replaced.
The reality is more specific to each application.
For aerospace thermal-barrier coatings, alternative ceramic systems may reduce reliance on yttrium-containing formulations in some use cases. But changing a coating can affect heat resistance, durability, oxidation performance, maintenance intervals, and operating life.
A material can therefore have a technically available substitute without that substitute being economically or operationally equivalent.
This is especially important in aerospace because certification cycles can take years.
A manufacturer may choose to continue paying a higher price for an existing material rather than accept the cost, engineering work, testing, and certification required to replace it.
That creates a lag between commodity-price pressure and actual demand destruction.
Tungsten Is a Good Example of Why Substitution Risk Varies
China produced an estimated 82% of global mined tungsten in 2024.
Tungsten is valued for a combination of characteristics that are difficult to reproduce in a single replacement material:
- very high melting point
- high density
- hardness
- wear resistance
- strength at elevated temperatures
These properties support its use in cutting tools, wear-resistant components, aerospace, defense, electronics, and high-temperature systems.
In applications where the physical requirements are strict, the question may not be whether tungsten can be eliminated entirely, but whether less can be used or whether supply can be diversified.
That makes the investment case different from a mineral where downstream users can switch materials with relatively limited performance loss.
The Processing Bottleneck May Be More Important Than the Mine
This is another area where headline production statistics can be misleading.
A 2026 USGS study covering 77 mineral commodities found that China produced 74 of them and was the world’s leading producer for 39.
But mineral reserves are often far less concentrated than processing capacity.
China controlled 91% of rare-earth refining and 94% of sintered permanent-magnet production in 2024, compared with 60% of magnet rare-earth mining.
That gap explains why a Western mine can come into production without materially changing downstream dependence.
A complete non-Chinese supply chain requires:
- mining
- beneficiation
- chemical processing and separation
- oxide refining
- metal and alloy production
- component manufacturing
- customer qualification
Each stage requires capital, technical expertise, permitting, and customers willing to support the supply chain.
For public-market investors, this means midstream and downstream capacity can sometimes be more strategically valuable than the mineral deposit itself.
What This Means for Critical-Mineral Investors
The aerospace example adds another variable to the critical-mineral investment framework.
A mineral can benefit from supply concentration and strategic demand, but that does not automatically create a strong long-term investment case.
Investors need to consider at least four factors:
Supply concentration How much mining, refining, or component manufacturing is concentrated in China or another single jurisdiction?
Substitutability Can end users switch to another material without sacrificing performance?
Qualification time Even if a substitute exists, how long will it take customers to approve it?
Price sensitivity At what price does substitution, recycling, or redesign become economically attractive?
The strongest supply-security cases are likely to be those where concentration is high, substitution is technically difficult, downstream capacity is limited, and customers have strong reasons to secure supply regardless of short-term pricing.
The Investor Takeaway
Aerospace suppliers testing alternative coatings do not invalidate the critical-minerals thesis.
They show why the thesis needs to be more selective.
Higher prices and supply restrictions encourage three responses at the same time:
- development of new mines and processing capacity
- recycling
- reduction of material intensity through substitution and redesign
Some minerals will be more exposed to substitution than others.
For materials with limited technical alternatives, long qualification cycles, and concentrated processing capacity, supply security can remain a major driver even when prices rise substantially.
For materials where alternative technologies can be adopted more easily, high prices may eventually weaken demand growth.
The key question for investors is therefore not simply whether a mineral is classified as critical. It is whether the underlying application can realistically function without it, how quickly that change can happen, and where the bottleneck sits in the supply chain.
This material is provided for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security.
About AER Insights
Alliance Equity Research publishes timely insights on company-specific developments, industry trends, capital markets activity, and emerging investment themes across global public markets, with a particular focus on undercovered companies, sectors, and developments that often receive limited attention from mainstream financial research. Our analysis focuses on the financial, strategic, and valuation implications behind the headlines, using company disclosures, filings, market data, and sector context to help investors understand what matters, why it matters, and what to watch next.
Get AER Insights by Email
Receive new AER Insights and research updates in your inbox.
Related Insights
 Biotechnology & Healthcare
SELLAS Reports a Survival Benefit in AML as Its Cancer Vaccine Approaches FDA Review
SELLAS Life Sciences reported that its investigational cancer vaccine met the overall-survival endpoint in a Phase 3 trial of patients with acute myeloid leukemia who had reached a second or later remission and could not undergo a donor stem cell transplant. Median survival was 24.0 months with galinpepimut-S versus 14.7 months with investigator-selected care. The result provides a basis for a planned FDA discussion, while detailed control-arm, safety and secondary-endpoint data remain important to interpretation. SELLAS ended September with $134.7 million in cash after substantial warrant exercises.
 Biotechnology & Healthcare
Helus Pharma’s Depression Trial Succeeds as Safety and Funding Questions Move Forward
Helus Pharma’s HLP003 met the primary endpoint in its first pivotal depression trial, producing a 7.6-point advantage over placebo on a symptom scale at six weeks. Patients remained on their existing antidepressants, and the benefit persisted at the study’s 12-week assessment. The results strengthen the case for an intermittent add-on treatment, although the nature of three treatment-related serious adverse events remains undisclosed. Quarterly filings show $171.1 million in cash at September 30 and continued clinical spending ahead of a second pivotal readout expected in late 2027.
 Mining & Critical Minerals
Atalaya Adds Two Spanish Copper Projects as Its Growth Pipeline Competes for Capital
Atalaya Mining has acquired the former Tharsis and La Zarza mines in southern Spain for €125 million, adding large copper-bearing resources to a portfolio already led by its operating Riotinto complex and the proposed Touro development. The purchase follows a quarter of record EBITDA, helped by higher copper prices and increased sales. Although Atalaya paid €75 million upfront from cash, another €50 million is due within a year. The value of the expansion will depend on permitting, processing economics and how the new assets fit alongside existing investment priorities.
 Mining & Critical Minerals
Meridian’s Cabaçal Financing Offers Advance a Mine With Important Terms Unsettled
Meridian Mining has appointed an engineering and construction management contractor for its Cabaçal copper-gold project in Brazil and received indicative financing proposals, including packages totaling $400 million. The project’s feasibility study models a $2.09 billion after-tax net present value, but its initial capital estimate relies on tax credits and excludes financing charges. The financing offers remain subject to negotiation, while the mine installation permit was under review in the October technical report. The crucial issue for investors is how much of the modeled project value Meridian can retain after construction funding, sales arrangements and other obligations are settled.
About Alliance Equity Research
Alliance Equity Research publishes independent and company-sponsored equity research on undercovered, emerging, and high-potential public companies globally. Our analyst-built, model-backed research combines fundamental business analysis, financial forecasting, and valuation.
Email: info@alliancekp.com · Website: https://allianceequityresearch.com
For detailed company research, financial models, or coverage inquiries, contact our research team.
Research commentary for informational purposes. This document does not constitute personalized investment advice or a Buy, Hold, or Sell recommendation. For important disclosures, including information about research sponsorship and potential conflicts of interest, visit allianceequityresearch.com/disclosures.